

B9: Cash Advance

- 7.45K Reviews
- 4.6
- Downloads
- 1,000,000+
Our take on B9: Cash Advance from Appgk
When money is tight between paydays, the hardest part is often not planning a budget but dealing with the awkward gap between an expense arriving and your wages becoming available. B9: Cash Advance is built around that specific problem. I see it as a finance app for people who occasionally need earlier access to part of their paycheck, rather than as a replacement for a full budgeting service or a long-term borrowing solution.
My first impression is that its appeal comes from focus. The app does not try to be a complete bank, investment platform, or spreadsheet-based money manager. Its central idea is straightforward: request a cash advance before payday and use it to handle a short-term need. That narrow purpose makes it easier to understand than many financial apps, but it also means the value depends heavily on your income pattern, eligibility, repayment timing, and ability to avoid repeating the cycle.
How B9 feels when your finances depend on a live connection
The important moments happen online
A cash-advance service is naturally more dependent on current information than a simple calculator. When I think about using B9, the key moments are checking what is available, reviewing the request, confirming account-related details, and seeing whether the advance has progressed. Those are not activities I would want to treat like an offline note-taking task. The app needs a current view of financial information, so a stable connection becomes part of the experience rather than a minor convenience.
This matters most when the request is urgent. If a bill is due the same day, I would not wait until the last minute to open the app, particularly in a place with unreliable reception. A weak connection can leave a screen loading, delay an update, or make it unclear whether an action has completed. With a finance app, uncertainty is more uncomfortable than it is in a game or social app because the result can affect a real payment decision.
Best Parts of B9: Cash Advance
Things to Keep in Mind About B9: Cash Advance
I recommend opening B9 before the pressure peaks. Check the available information while you have dependable Wi-Fi or mobile data, read the details carefully, and leave enough time to respond if the app asks for another step. That is a more sensible workflow than assuming an advance can be arranged instantly from any location. The app’s purpose is convenient, but convenience still depends on the phone being connected and the service being able to process current information.
Using it during ordinary mobile situations
The mobile format makes sense for the problem B9 addresses. People usually notice a shortfall while commuting, shopping, paying a bill, or managing an unexpected household expense, not while sitting at a desktop with a carefully prepared financial file. Being able to check the app from a phone can make the decision feel more immediate and practical.
News and Features Related to B9: Cash Advance

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Still, I would avoid making a rushed request while walking through a crowded station or standing at a checkout. Financial details deserve a private moment, and a noisy environment increases the chance of tapping through information without reading it. My preferred routine would be to stop somewhere secure, connect to a reliable network, review the amount and timing, and only then continue.
A realistic example is a mid-month utility payment that arrives before your normal payday. If your income is regular and the expense is genuinely temporary, B9 may help you bridge that timing mismatch. I would first compare the amount needed with the money expected on payday, then consider whether the next pay cycle will still cover rent, food, transport, and other fixed commitments. The useful question is not simply “Can I access money now?” but “Will accessing it now leave me short later?”
Don't want to read the full review?
This distinction is especially important because a cash advance can make an immediate problem look solved while moving the pressure forward. I find B9 more suitable for a controlled, occasional gap than for covering the same recurring deficit every pay period. If the app becomes part of a permanent pattern, the underlying budget problem deserves attention instead.
What happens when the connection or process breaks
One area where I would stay cautious is recovery after an interrupted session. If the signal drops while you are reviewing or submitting a request, I would not immediately repeat every tap. First, reconnect and reopen the relevant screen to see whether the status has updated. Submitting the same action repeatedly can create confusion, especially when the first attempt may already have reached the service.
Screenshots
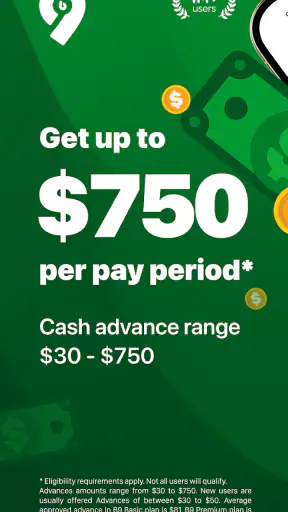
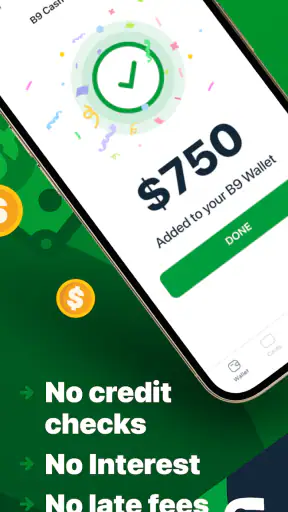
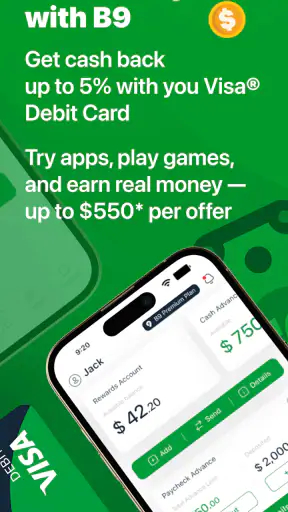
I also recommend keeping a simple personal note of what you intended to request and when you started the process. That is not a feature claim about B9; it is a practical habit that helps you distinguish between a failed attempt, a pending update, and a completed action. Screenshots can also be useful for your own records when they do not expose sensitive information to other people.
If the app does not refresh, I would move from mobile data to trusted Wi-Fi, restart the app, and check again later rather than making a financial decision based on an old screen. Avoid public networks when handling account information. A fast connection is not automatically a safe connection, and a finance app deserves the same care as mobile banking.
The recovery issue also changes how I would plan around a deadline. I would not request an advance minutes before a late fee or essential payment is due and assume the process will always be immediate. B9 can be convenient, but no connected finance service should be treated as a guarantee against every delay. Leaving a buffer is one of the simplest ways to reduce stress.
How to use less data without losing awareness
For most users, the main data-conscious habit is not constantly refreshing the app. Open it when you have a specific question: what is available, what action is required, or whether the status has changed. Repeatedly checking while travelling can use mobile data without giving you more certainty, particularly if the underlying information has not changed.
I would also avoid switching between several apps while a financial screen is loading. A stable connection and a little patience are preferable to repeatedly closing and reopening the process. If you are on a limited mobile plan, use a trusted Wi-Fi connection for account review when practical, but do not postpone an important check solely to save a small amount of data.
There is a useful trade-off here. Data saving should never mean ignoring a status update or failing to review repayment details. The better approach is deliberate use: prepare your questions first, open B9 once, read the information fully, and record the decision. That gives you more control than treating the app as something to monitor continuously.
I would also keep notifications and account alerts in perspective. If the app presents an update, read it rather than relying on memory from an earlier visit. Financial timing can change the usefulness of an advance, so an old assumption is not a safe substitute for current information. The app is most helpful when I use it as a decision tool, not merely as a button for obtaining money.
What the app is, and what it is not
B9 sits in the finance category and is developed by B9 - Get Your Paycheck Early. It is free to install and has an Everyone content rating, which makes it broadly approachable from an app-store perspective. Its popularity is substantial, with over a million installs, an average rating of 4.6 from around eighteen thousand ratings, and roughly seven thousand reviews. Those figures suggest that many people find the concept useful, although they do not tell me whether it will fit every person’s income arrangement or financial habits.
The app first appeared on August 3, 2021, and the current version is 3.70.0 for devices running Android 8.0 or later. That is helpful if you are checking compatibility before installing, especially on an older phone. On iOS or Android, I would still keep the operating system current where possible and install the app through the normal official store route rather than relying on an unfamiliar download source.
Compared with a traditional bank overdraft, B9 is more focused on accessing pay earlier instead of treating the account as a general-purpose borrowing facility. Compared with a budgeting app, it addresses liquidity rather than helping you map every category of spending. Compared with borrowing from a friend or family member, it offers a more structured digital route, but it also requires you to understand the app’s conditions and the effect on your next payday.
That comparison reveals the main trade-off. A budget app may be better if your real need is visibility and planning. A bank product may be better if you need a broader account relationship or a longer-term financial solution. B9 is more compelling when the problem is specifically the timing of earned pay and the amount needed is manageable within the next pay cycle.
Who I would recommend it to
I would point B9 toward someone with predictable pay who occasionally faces a short gap before payday. The strongest use case is a defined expense with a clear repayment plan: an essential purchase, a timing mismatch, or a short-lived emergency that does not represent a permanent increase in monthly spending.
I would also recommend treating the first use as a learning exercise. Before requesting anything, write down the expense, the amount required, the date your income normally arrives, and the bills that follow. Then ask whether the advance solves a one-off timing issue or merely postpones a shortage. This simple check is more valuable than focusing only on how quickly the money may become available.
On the other hand, I would be careful recommending it to someone whose income changes sharply from one pay period to the next, or to anyone already using several forms of short-term credit. A new advance can add another date to remember and another obligation to manage. If you are borrowing to cover essentials every month, a conversation with a financial counselor or a more complete budgeting review may be more useful than another advance request.
I would also skip it if you are looking for investing tools, detailed expense categorization, credit-building education, or a conventional savings system. B9’s focused purpose is a strength for the right user, but it is not a reason to expect features from unrelated finance categories.
Practical habits that make the experience safer
My first tip is to decide the maximum amount before opening the app. Starting with the amount you need, rather than the largest amount you might be offered, reduces the temptation to turn a small gap into extra spending money. The second is to check the next payday as part of the same decision. An advance is only comfortable when the following pay cycle remains workable after ordinary expenses.
My third tip is to use a two-stage routine: review first, request second. On the first pass, I would read the available terms, timing information, and any repayment implications. On the second pass, I would act only after checking the figures against my own budget. This separation is particularly useful on a small phone screen, where it is easy to move quickly through a process designed for convenience.
A fourth useful habit is to avoid using a weak connection for the final step. If you are in an elevator, underground station, or crowded event, wait until you can confirm that the app has loaded properly. If something appears stuck, do not assume the request failed or succeeded until the status is clear. That small pause can prevent duplicate actions and unnecessary anxiety.
Finally, I would review the app after the immediate problem is over. Did the advance solve the issue cleanly? Did it make the next payday uncomfortable? Did you need more than expected? Those answers tell you whether B9 is serving as an occasional bridge or becoming part of a costly routine. The most responsible use is one that becomes less necessary over time, not one that quietly expands with every pay cycle.
My connectivity verdict
B9: Cash Advance makes the most sense when you need a mobile way to manage a short-term pay-timing problem and can make decisions while connected, calm, and aware of the next repayment pressure. Its focused design is easier to understand than a broad financial suite, and its large user base and strong average rating indicate that the basic idea resonates with many people.
My reservation is not about the convenience of the concept; it is about relying on any connected advance service during a financial emergency without preparation. Network interruptions, delayed status updates, privacy concerns in public places, and the temptation to borrow more than necessary all matter. I would use B9 with a stable connection, a written plan, and a clear limit.
My bottom line: B9 is best viewed as an occasional bridge, not a permanent extension of your paycheck. If your income is dependable and the gap is temporary, it can be a practical option to investigate. If the same shortfall returns every pay period, a budgeting solution, a conversation with your bank, or broader financial support is likely to be the better next step.
B9: Cash Advance FAQ
What is B9: Cash Advance, and how does it work?
B9: Cash Advance is a financial app designed to give eligible users early access to part of their expected paycheck, along with banking-related features such as direct deposit and a debit card. After signing up, you provide personal and employment information for verification. If approved, the available advance depends on factors such as your income, deposit history, account activity, and B9’s current eligibility requirements.
How much money can I receive through B9, and when will I get it?
The amount available through B9 is not the same for every user. Your potential advance is generally determined by verified income, payroll deposits, account history, and other risk factors. Delivery speed can also vary. Some transfers may arrive quickly, while others can take longer depending on verification, banking networks, weekends, holidays, and the transfer method selected. Always review the app before accepting an advance.
Does B9: Cash Advance charge fees or require a subscription?
B9 may use a membership or subscription-based pricing model, and additional charges can apply depending on the services you use, such as expedited transfers or other account features. Pricing, plan benefits, and eligibility terms may change over time. Before downloading or requesting money, carefully check the current fee schedule, recurring membership cost, transfer charges, and cancellation rules shown in the app or official terms.
Will using B9 affect my credit score?
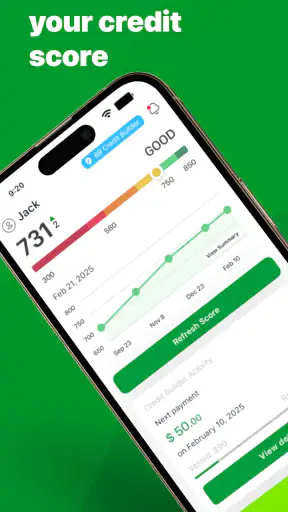
Cash advances from services such as B9 are typically not traditional loans and may not involve a standard hard credit inquiry, so using the service may not directly affect your credit score in the same way as applying for a credit card or personal loan. However, policies can change, and missed obligations, linked-account issues, or other financial activity may still create problems. Read B9’s current disclosures before proceeding.
Is B9: Cash Advance safe, and what information does it require?
B9 uses personal and financial information to verify your identity, evaluate eligibility, and provide account services. You may be asked for details such as your legal name, address, identification information, employment data, and bank or payroll access. Use only the official app-store listing and review permissions carefully. Also enable security protections, avoid sharing login codes, and read the privacy policy to understand how your data is handled.











